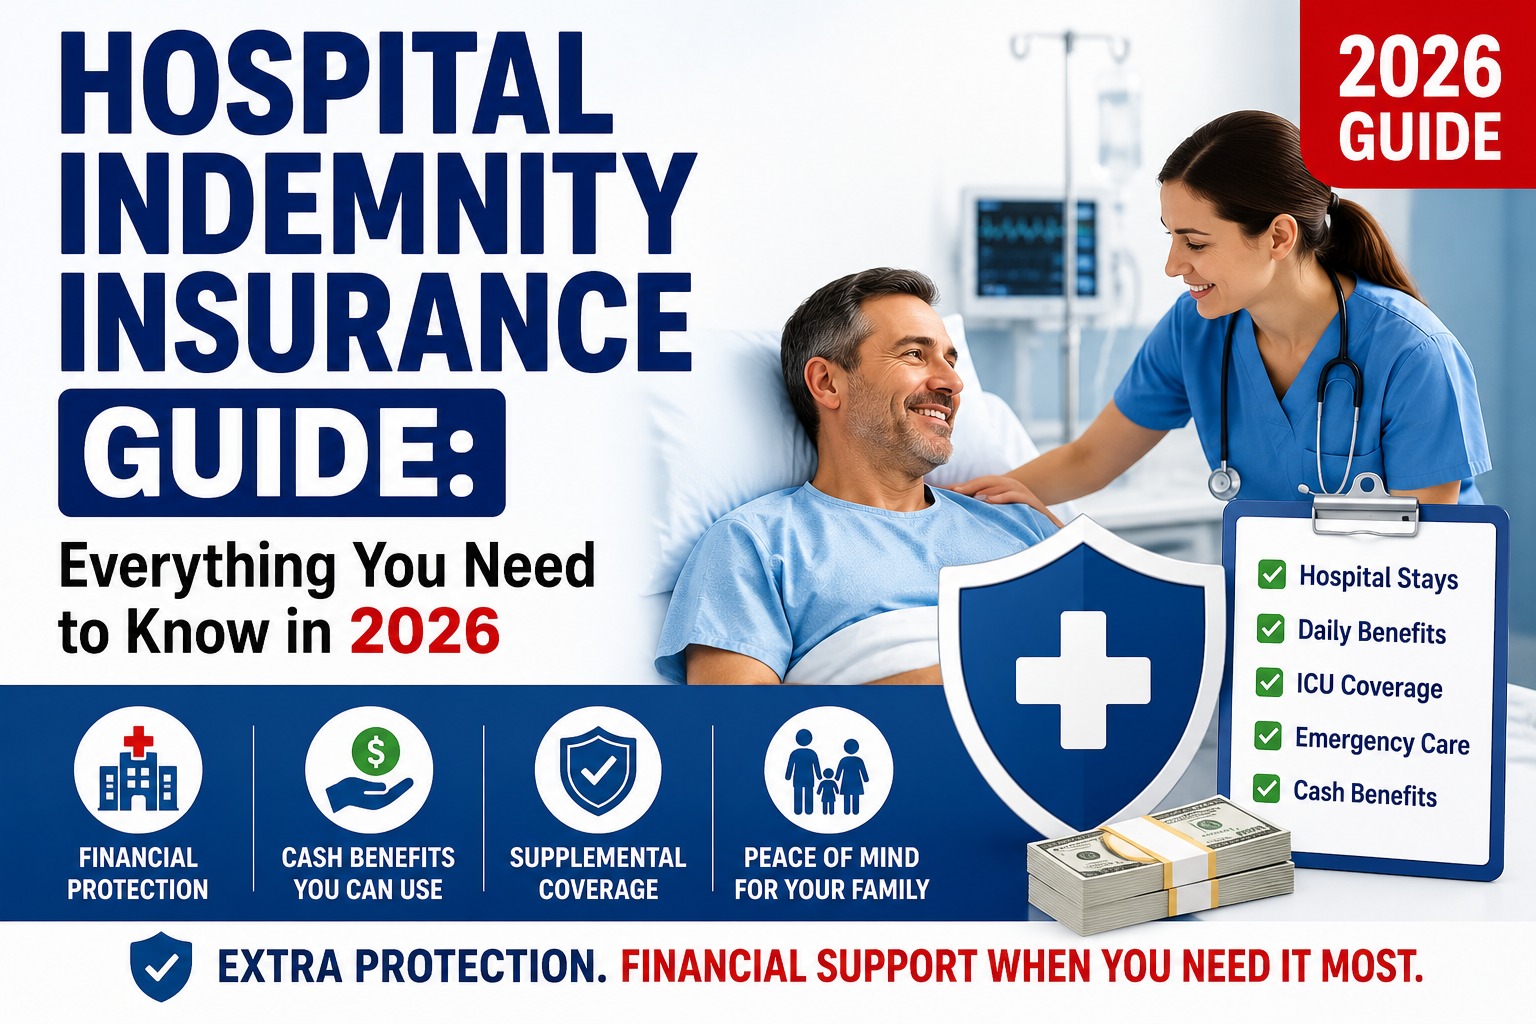
Hospital Indemnity Insurance Guide: Everything You Need to Know in 2026
Hospital indemnity insurance is a type of supplemental health insurance that can provide a fixed cash benefit when you are admitted to a hospital or receive certain covered medical services.
Unlike traditional health insurance, the benefit is generally paid directly to the policyholder, who can use the money for eligible expenses such as deductibles, copayments, transportation, household bills, or other costs.
What Is Hospital Indemnity Insurance?
Hospital indemnity insurance provides a predetermined cash benefit for covered hospital-related events.
Depending on the policy, benefits may be available for:
- Hospital admission
- Hospital stays
- Intensive care
- Certain surgeries
- Emergency room visits
- Outpatient procedures
- Ambulance services
Coverage varies by insurance company and policy.
How Does Hospital Indemnity Insurance Work?
The process is generally simple:
- You purchase a hospital indemnity policy.
- You are admitted to a hospital for a covered condition or service.
- You submit a claim to the insurance company.
- If the claim meets the policy requirements, you receive the applicable benefit.
- You can generally use the cash benefit for expenses not fully covered by your primary health insurance.
Benefits of Hospital Indemnity Insurance
Hospital indemnity coverage can provide additional financial protection during a hospital stay.
Helps With Out-of-Pocket Costs
The benefit can help cover expenses such as deductibles, copayments, and coinsurance.
Provides Cash Benefits
Payments are generally made directly to the insured rather than the hospital.
Extra Financial Protection
It can provide additional support when an unexpected hospitalization creates financial pressure.
Can Complement Existing Insurance
Hospital indemnity insurance is usually designed to supplement, not replace, major medical health insurance.
What Does Hospital Indemnity Insurance Cover?
Coverage depends on the specific policy, but may include:
- Hospital admission benefits
- Daily hospital confinement benefits
- ICU benefits
- Emergency room benefits
- Ambulance benefits
- Certain outpatient services
- Surgery benefits
Always check the policy documents for exact coverage and exclusions.
What Is Usually Not Covered?
Hospital indemnity policies may have limitations and exclusions.
Depending on the policy, they may include:
- Pre-existing condition limitations
- Non-covered treatments
- Certain elective procedures
- Services outside the policy’s covered benefits
- Waiting periods for specific conditions
Never assume a service is covered without checking the policy terms.
How Much Does Hospital Indemnity Insurance Cost?
Premiums vary based on factors such as:
- Age
- Location
- Coverage amount
- Benefit structure
- Individual or family coverage
- Insurance provider
The best way to compare plans is to look at both the premium and the benefits offered.
Who Should Consider Hospital Indemnity Insurance?
This type of supplemental coverage may be worth considering if you:
- Have a high-deductible health plan
- Want additional protection against hospital expenses
- Expect higher healthcare use
- Want financial support during hospitalization
- Prefer additional supplemental coverage
Hospital Indemnity vs Regular Health Insurance
| Feature | Hospital Indemnity | Regular Health Insurance |
|---|---|---|
| Main Purpose | Supplemental financial protection | Medical expense coverage |
| Payment | Fixed benefit for covered events | Pays covered medical expenses |
| Hospital Coverage | Specific benefits | Broader medical coverage |
| Replaces Major Medical Insurance | No | Yes |
| Cash Benefit | Generally Yes | Generally No |
How to Choose a Hospital Indemnity Plan
Before buying a policy, compare:
- Monthly premium
- Hospital admission benefit
- Daily hospital benefit
- ICU benefit
- Emergency care benefits
- Waiting periods
- Exclusions and limitations
- Benefit limits
- Claim process
- Overall value
Final Thoughts
Hospital indemnity insurance can provide an additional layer of financial protection when an unexpected hospitalization occurs. It can be particularly useful for people who want help managing deductibles, copayments, and other expenses that may arise during a hospital stay.
However, it is supplemental coverage and generally should not be considered a replacement for comprehensive health insurance.
Before purchasing a plan, carefully compare the premium, covered benefits, exclusions, waiting periods, and benefit amounts to determine whether it fits your healthcare and financial needs.